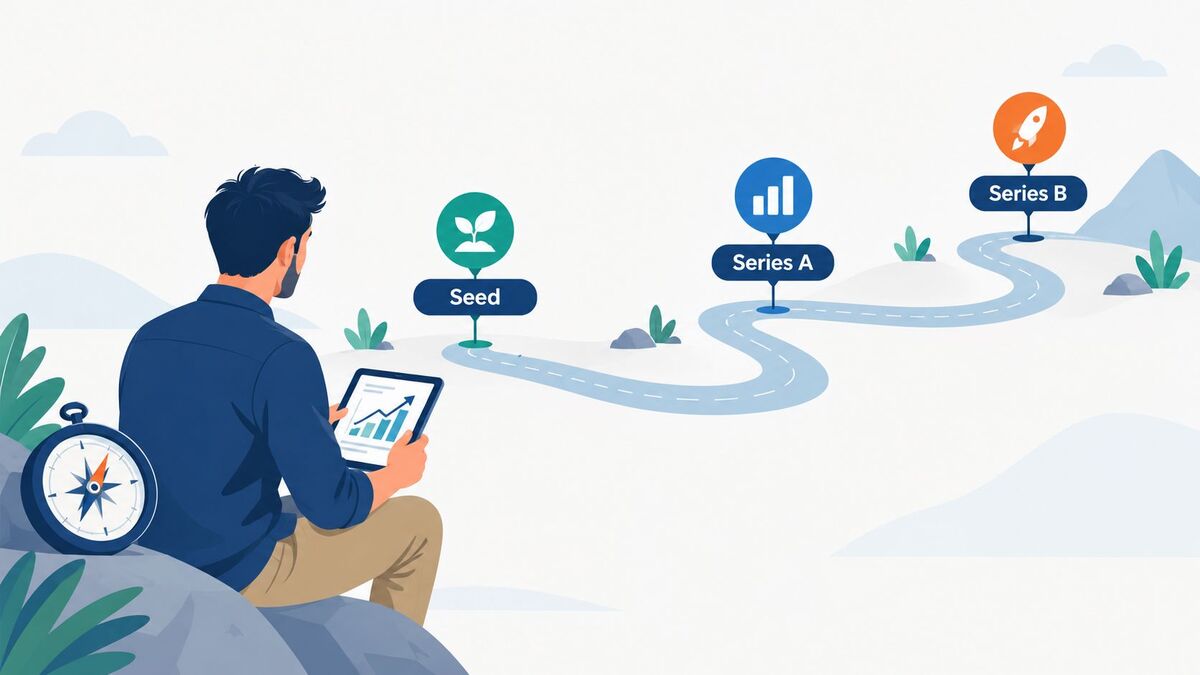
Most founders don’t have a funding problem. They have a matching problem: the wrong type of money, at the wrong stage, for the wrong goal.
That is the idea behind growth navigate funding. If you searched the phrase and found vague answers, there is a reason. It isn’t an official finance category like a Series A or a term loan. It is a way of thinking about capital: decide where your business needs to go next, then choose the funding that gets you there without creating new problems.
This guide covers what the term means, who it suits, which funding options fit which situations, which metrics investors check first, and how to prepare for a round. It also lists the mistakes that most often derail funding plans.
What Is Growth Navigate Funding? A Plain-English Definition
Growth navigate funding is a structured approach to raising and using capital as a business moves from early traction to scale. Instead of asking “how much can I raise?”, it starts with “what does my business need to prove next, and what is the cheapest, safest capital to prove it?”
Think of a road trip. You choose the destination before buying fuel. Funding works the same way: know the milestone before you raise the money.
The approach rests on three questions:
- What is the next milestone? For example, launching a product, reaching 100 paying customers, or entering a new market.
- What will it cost to get there? Include salaries, marketing, tools, and a safety buffer.
- Which funding source fits that cost and risk? Equity, debt, grants, or revenue can all work.
“Growth Navigate” is also the name of an advisory business online. This article covers the general concept, not any one company’s services.
Is It a Real Funding Type or a Capital Planning Framework?
It is a planning framework, not a financial product. You can’t apply for “growth navigate funding” at a bank the way you would apply for a business loan.
Some online guides imply it is a specific program or loan type, which can mislead readers. What you can do is use the framework to decide which real products to pursue, such as venture capital, bank loans, government grants, or revenue-based financing.
It works as the strategy layer above the funding itself. The framework tells you what to look for, and the funding products are what you actually apply for.
Who Needs It: Startups, Small Businesses and Scaling Teams
The framework is most useful at a turning point, when the old way of funding the business stops working.
- Early-stage startups use it to avoid raising too much too soon, which can mean heavy dilution and pressure to grow at any cost.
- Small and medium businesses (SMEs) use it to choose between loans, grants, and reinvesting profit. A bakery opening a second location has very different needs from a software company hiring ten engineers.
- Scaling teams use it to time larger rounds. If your payback period is long, it often makes sense to fix retention or pricing first, then raise.
A freelancer with steady income and no major expansion plans probably doesn’t need a formal funding strategy yet.
How Growth Navigate Funding Works From Seed to Series B
The approach changes as the company matures.
Pre-seed and seed: prove the idea
Early money is validation capital. The goal is evidence that people want what you are building. Typical sources are founder savings, angel investors, grants, and small seed rounds.
Series A: prove the model
Here you show that the business can grow repeatably. Investors look for recurring revenue, healthy retention, and a clear customer acquisition channel.
Series B and beyond: scale what works
This is execution capital. You already know what works, and the funding pays to do more of it faster through new markets, bigger teams, and stronger sales.
Each stage should prove something specific before you raise again. When funding is tied to milestones, rounds tend to go better and surprises are fewer.
Main Funding Options: Equity, Debt, Grants and Revenue-Based Financing
Each route has trade-offs.
| Option | Best for | Main trade-off |
| Equity (VC or angel) | High-risk, fast-growth plans | You give up ownership and some control |
| Debt (loans, credit lines) | Predictable, cash-generating businesses | Repayments are fixed, whatever happens |
| Grants | Research, innovation, regional programs | Competitive, slow, and restricted in use |
| Revenue-based financing | Businesses with steady recurring revenue | Part of future revenue goes to repayment |
| Bootstrapping | Founders who want full control | Slower growth, limited by your own cash |
Equity suits ventures with large upside and high risk, since there is no fixed repayment. Debt suits businesses with reliable cash flow. Grants cost no ownership, but they come with paperwork and strict rules on how the money is spent.
Many companies blend these over time. A common path is grants and savings early, equity once traction appears, and debt later to fund working capital.
Matching Capital to Your Next Business Milestone
This is the core of the framework. Start with the outcome, then work backward to the amount.
Say you run a subscription app and want to double your user base. Ask:
- What will it take? For example, more marketing spend and one extra engineer.
- How much will that cost over 12 to 18 months?
- What result would prove it worked, and by when?
If the answer is a modest, short-term spend with fast payback, debt or revenue-based financing may be enough. If the plan needs a large, uncertain bet, equity is more likely.
Tie each chunk of money to a specific milestone, such as a product launch, a customer target, or a revenue figure. Investors respond well to this because it shows discipline.
Unit Economics and Metrics Investors Look at First
Before anyone commits money, they want to know whether growth is efficient. These numbers come up most:
- Customer acquisition cost (CAC): what you spend to win one customer.
- Lifetime value (LTV): what a customer is worth over time. A common rule of thumb is an LTV to CAC ratio of around 3:1 or better.
- Payback period: how long it takes to earn back your acquisition cost. Shorter is safer.
- Churn and retention: how many customers stay. High churn makes growth expensive.
- Burn multiple: how much cash you burn for each dollar of new revenue. Lower is better.
These benchmarks vary by industry and stage, so treat them as guides, not pass-or-fail tests.
If your numbers are weak, improving them often beats raising money. Fixing churn or pricing before approaching investors can raise your valuation and your odds of success.
Step-by-Step: How to Prepare for a Funding Round
Good preparation can shorten the process and improve your terms.
- Define the goal. Write one sentence on what the money will achieve.
- Clean up your financials. Have accurate revenue, expense, and cash flow records ready.
- Know your metrics. Be able to explain CAC, LTV, churn, and burn without checking notes.
- Build a simple funding plan. Include how much you need, how you will use it, and what milestones it unlocks.
- Prepare your pitch materials. A concise deck, a one-page summary, and a financial model are usually enough.
- Research the right funders. Target investors or lenders who back your stage and industry.
- Leave buffer time. Raising often takes longer than expected, so don’t wait until cash is nearly gone.
Common Funding Mistakes That Slow Down Growth
Most of these errors are avoidable:
- Raising before knowing the purpose. Money without a plan tends to be spent without results.
- Choosing the wrong instrument. Taking equity for a predictable, low-risk expansion can cost far more than a loan.
- Ignoring dilution. Small percentages add up quickly across several rounds.
- Hiding weak metrics. Investors will find them, and lost trust is hard to rebuild.
- Running out of runway. Negotiating from a weak position usually means worse terms.
- Chasing every investor. A focused list of relevant funders beats a mass email.
Do You Need a Funding Advisor? What to Check First
An advisor can help if you lack funding experience or time, but many founders manage well on their own with good research.
Consider one when the round is complex, you need introductions, or your financial models need work. Before hiring, check:
- Their track record with businesses at your stage
- How they charge (flat fee, retainer, or success fee) and what that means for their incentives
- Whether they can show real results and references
- What they will do versus what you will still need to handle
Be cautious of anyone who guarantees funding. No honest advisor can promise that.
FAQs
Is growth navigate funding a loan?
No. It is a planning framework for choosing capital, not a loan or investment product. You use it to decide whether to pursue loans, equity, grants, or other sources.
How much funding does a growing business need?
It depends on your milestone. Estimate your costs for the next 12 to 18 months, add a safety buffer, and work back from the result you need to prove.
What is the difference between equity and debt funding?
Equity means selling a share of your business in exchange for capital, with no fixed repayment. Debt means borrowing money that you repay with interest, while keeping ownership.
When is the right time to raise money?
Ideally when you have clear traction, a defined use for the funds, and enough runway to negotiate without pressure. Raising from a position of strength usually means better terms.
Can small businesses use this approach?
Yes. Matching funding to a milestone works for any business planning to grow, not only venture-backed startups.
Conclusion: Is Growth Navigate Funding the Right Path for You?
Growth navigate funding isn’t a secret program or a special product. It is a disciplined way to approach money: start with the milestone, choose capital that fits the risk, and keep your numbers in order.
If you are heading into a growth stage, begin with one question: what does my business need to prove next? Answer it honestly, and the right funding choice usually becomes much clearer.